ReFuelEU Aviation Targets Met in 2025, Data Shows
The inaugural ReFuelEU Aviation report reveals the EU exceeded its 2025 SAF target but faces supply chain issues.
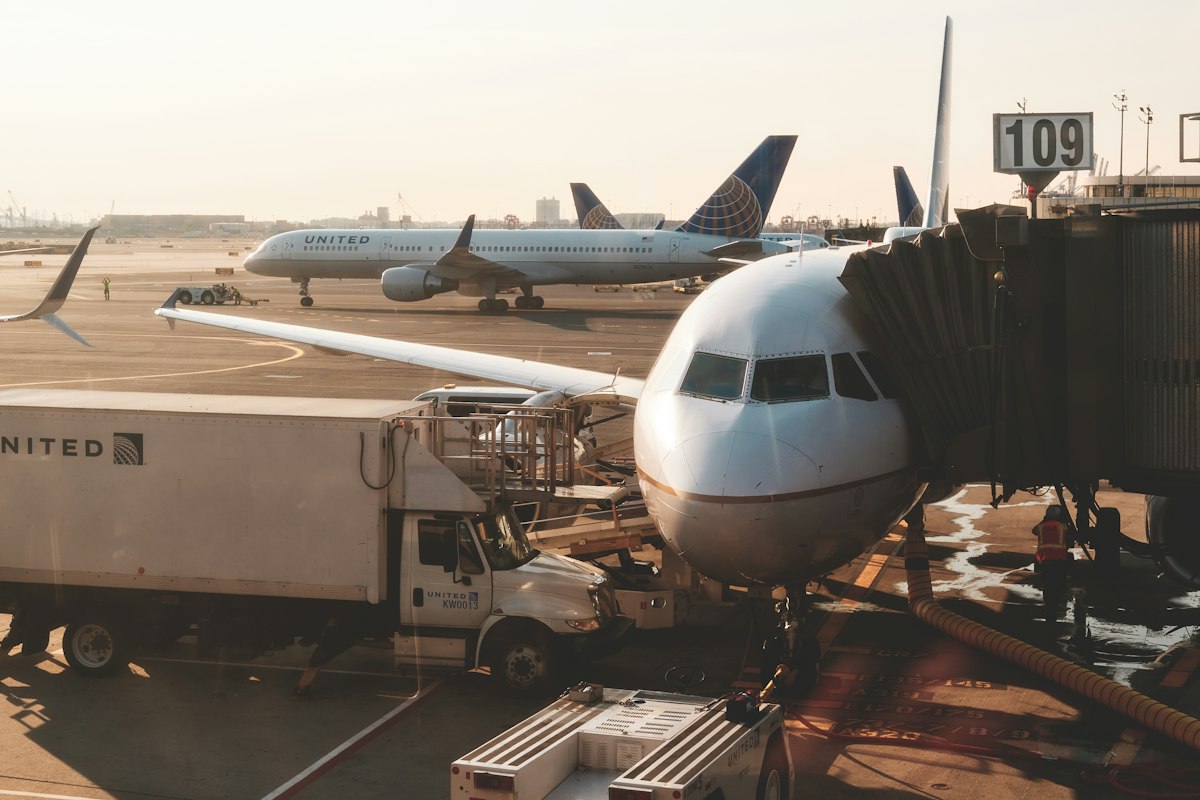
The targets were met. And exceeded. ReFuelEU Aviation's goals for 2025, in their very first year of implementation, have now been surpassed, according to newly released data showing that sustainable aviation fuel made up 2.8 percent of the total aviation fuel supplied at European Union airports during 2025. That's a big jump. It's up from the 0.6 percent share recorded in 2024. So it comfortably surpasses the legally mandated 2 percent target set for the year, a mark officials can't ignore.
The numbers prove that clear regulatory mandates can rapidly accelerate market adoption. Roughly 1.1 million tonnes of sustainable aviation fuel flowed through European Union airports over the course of 2025. This initial success demonstrates that airlines and suppliers can adapt when faced with binding policy rules. However, beneath the positive headline numbers lie serious vulnerabilities in the supply chain that could threaten long-term climate goals.
Heavy reliance on imported waste oils
HEFA dominates. That's the reality for sustainable fuel at European airports, where one production pathway, hydroprocessed esters and fatty acids, supplies the vast majority of what's currently on the market. And it leans hard on waste oils and fats, which raises serious questions about long-term scalability. Used cooking oil alone accounts for roughly 80 percent of the sustainable aviation fuel supplied in the European Union, so we've got a market that's narrow, dependent, and vulnerable. It's a concentration problem.
This massive concentration creates serious vulnerabilities. It's a real problem. Industry experts point to widespread risks of fraud and misclassification within international waste oil supply chains, and they're warning that these dangers run through the entire system. And these materials are scarce. So relying on them as the foundation for decarbonizing flight is highly risky. We've got a limited resource, and we can't pretend it's a safe bet.
Other feedstocks are rising fast. Category 3 animal fats now make up about 11 percent of the European sustainable aviation fuel supply, but these fats are already used by other mature industries, since oleochemical manufacturers, animal feed producers, and other biofuel sectors rely on these same materials. Diverting them to airplanes doesn't eliminate emissions. It just shifts them. And they're moved to other sectors of the economy.
The growing footprint of palm products
Palm oil mill effluent is now part of the fuel mix. It's a by-product of palm oil production, and it now accounts for roughly 6 percent of the sustainable aviation fuel supply in Europe, a share that has grown as the industry looks for waste-based feedstocks that don't compete with food crops. So it's a major component.
This trend links aviation directly to the environmental impacts of the palm oil industry. And it's not just about feedstocks. The geographic origin of these materials reveals a deep dependency on foreign markets, one that ties the future of sustainable flight to supply chains stretching far beyond Europe's borders. While 84 percent of the sustainable aviation fuel is refined inside the European Union, 85 percent of the feedstocks used to make it are imported from abroad. That's up sharply. It's a jump from the 69 percent import rate recorded the previous year, a figure that shows just how much the bloc now relies on outside suppliers. China remains the primary source for these imported materials.
"Europe is therefore building a SAF market that remains heavily dependent on imported feedstocks whose availability is limited and whose sustainability credentials are increasingly under scrutiny. This is not a credible long-term strategy for decarbonising European aviation."
This warning came from Camille Mutrelle. She's an aviation policy manager. It highlights the fragile foundation of the current market. Without domestic feedstock diversification, the system remains fragile, and that's the core problem we've got to face, because nothing about this setup holds up if the feedstock sources don't change. And they don't.
Synthetic fuels face investment deadlock
The most worrying gap in the European transition? It's the complete lack of commercial-scale synthetic aviation fuel production. And these synthetic fuels, known as e-SAF, which are seen by many as vital for deep decarbonization and which the industry keeps waiting for, still don't exist at the scale anyone needs. No production. We've got nothing.
Project planning is active. Actual building has stalled. Assessments show that about 60 e-SAF projects are currently in development across Europe, yet not a single one of these projects has reached a final investment decision. That freeze threatens future targets. Projections indicate that every single project currently classified as highly credible must begin construction soon to meet upcoming European synthetic fuel targets, and it's a deadline they don't have room to miss.
A summary of the current fuel mix
- Used cooking oil makes up 80 percent of the European sustainable aviation fuel supply.
- Category 3 animal fats account for 11 percent of the market.
- Palm oil mill effluent has climbed to a 6 percent share.
- Imported feedstocks represent 85 percent of the total supply chain, with China acting as the primary source.
Three paths forward for European policy
Supply chain bottlenecks won't fix themselves. To resolve these supply chain bottlenecks, European policymakers must focus on three distinct areas, and they can't afford to treat any of them as optional. First, they must protect the existing regulatory framework. Weakening the e-SAF sub-targets would be a mistake. And it's a mistake they'd make in response to low investment. Investors need long-term certainty that these mandates will remain in place to justify spending capital on new refineries.
Second, Europe must bridge the gap. That gap is between announcements and construction. De-risking mechanisms can give developers the financial certainty they need, and it's clear that without that certainty, projects stall before a single foundation is poured. A pilot double-sided auction planned in Germany represents a solid start. But broader action is required. An EU-wide market intermediary running similar double-sided auctions could pool demand, and that pooled demand, if it's organized well and backed by real political will, could unlock the first wave of commercial plants.
Finally, we must act. There must be a concerted effort to move away from imported waste oils, and that effort can't be half-hearted. The European Commission has proposed phasing out Emissions Trading System support for used cooking oil-based fuels starting in 2030. That's the shift. It's a policy change that could provide the necessary incentive to push the market toward more sustainable, diverse, and domestic fuel pathways, though we've yet to see if it's enough. But it's a start.
Frequently Asked Questions
What share of total aviation fuel supplied at European Union airports did sustainable aviation fuel make up in 2025, and how does that compare to 2024?
Sustainable aviation fuel made up 2.8 percent of the total aviation fuel supplied at European Union airports during 2025. That share was up from the 0.6 percent recorded in 2024, and it comfortably surpassed the legally mandated 2 percent target set for the year.
Why is the heavy concentration on used cooking oil considered a serious vulnerability for the European sustainable aviation fuel market?
Used cooking oil alone accounts for roughly 80 percent of the sustainable aviation fuel supplied in the European Union, creating a market that is narrow, dependent, and vulnerable. Industry experts point to widespread risks of fraud and misclassification within international waste oil supply chains, and these materials are scarce, making reliance on them highly risky.
How dependent is Europe on imported feedstocks for its sustainable aviation fuel, and which country is the primary source?
While 84 percent of the sustainable aviation fuel is refined inside the European Union, 85 percent of the feedstocks used to make it are imported from abroad, a jump from the 69 percent import rate recorded the previous year. China remains the primary source for these imported materials.
What is the current status of commercial-scale synthetic aviation fuel production in Europe, and what does that mean for future targets?
There is a complete lack of commercial-scale synthetic aviation fuel production, with no e-SAF production existing at the scale anyone needs. About 60 e-SAF projects are in development across Europe, yet not a single one has reached a final investment decision, and projections indicate every highly credible project must begin construction soon to meet upcoming European synthetic fuel targets.
Who warned that Europe is building a sustainable aviation fuel market heavily dependent on imported feedstocks, and what did they say about it?
Camille Mutrelle, an aviation policy manager, warned that Europe is building a SAF market that remains heavily dependent on imported feedstocks whose availability is limited and whose sustainability credentials are increasingly under scrutiny. She stated that this is not a credible long-term strategy for decarbonising European aviation.
Sebastian Wolf reports on the car industry, from performance machines to the engineering that powers them. He is fascinated by how manufacturers balance tradition with the rapid move to electrification.
💬 Comments (0)
No comments yet. Be the first!